You need to pay yourself as a self-employed therapist. But how, how much, and how often?
Gone are the days of simply receiving a paycheck from an employer. You’re your own boss now, and it’s up to you to make sure you follow best practices for bookkeeping, budgeting, and withholding taxes.
The exact method of paying yourself varies according to whether your practice is a sole proprietorship, an S corporation, or a limited liability company (LLC) filing as an S corp or disregarded entity.
Beyond that, it’s just a matter of following the right steps. Here’s how.
{{consult}}
How to pay yourself as a sole proprietor therapist
If you’re uncertain whether you are a sole proprietor, or if you’re not sure what the difference is between a sole prop and, say, a professional corporation, check out our article on how to choose a business entity as a therapist.
When you’re a sole proprietor, you and your therapy practice are, for tax purposes, identical. All income your therapy practice earns is de facto personal income, reported on your personal tax return (IRS Form 1040).
So, what’s the point of paying yourself at all?
Why you need to pay yourself as a sole proprietor
First things first: Whatever your business entity type, you should have a separate business bank account for all income you earn as a therapist. You should also pay your business expenses from the same account.
Why? To save time and avoid major mistakes.
When you pay your office rent and your apartment rent from the same bank account, it’s harder to keep track of which is which—both for the sake of bookkeeping, and for reporting deductible expenses on your tax return.
When income from your therapy practice transactions mingles with income from—for instance—selling your car, you could end up recording the sale price of a 2012 Prius as revenue on your practice’s books, skewing insights into how much your business is really earning.
For the sake of staying organized, all your therapy practice’s income should go into your business checking account. Until it leaves that account, it’s a business asset. It only leaves that account when it’s being used to cover a business expense. And your owner’s draw is a business expense. More on that in a moment.
Heard Banking* is purpose-built for this—a business checking account included with every Heard plan, with every transaction automatically categorized and synced to your bookkeeping.
When you keep your personal and business assets separated this way, bookkeeping is easy. If you use Heard without Heard Banking, we’ll automatically import all your transactions from your business bank account, categorize them, and use them to generate financial statements.
If you do your own bookkeeping using accounting software, it’s typically able to sync with your bank account—meaning you can import all your transactions, categorize them yourself, and create financial statements.
And if you work with a bookkeeper, they can use their own software to import the information from your account.
You have two options for paying yourself as a private therapist: taking owner’s draws, and paying yourself a salary. This article illustrates both, and helps you choose which option is right for you based on the specifics of your therapy practice.
Owner’s draw vs. salary for therapists
An owner’s draw is a withdrawal of funds from your business account for personal use. It can happen on a set schedule, or simply as needed.
A salary is just like a salary for any other employee. When you pay yourself a salary, you’re legally an employee of your own business.
Whether you pay yourself with an owner’s draw or a salary depends upon your business structure and your needs in terms of personal cash flow.
Here’s a closer look at the differences between owner’s draws and salaries.
How an owner’s draw works for therapists
Owner’s draws are typically favored by private therapists whose practices are pass-through entities. In that case, for tax purposes, the income of the business and the personal income of the therapist (or therapists, in the case of a partnership) is identical.
As a result, every dollar the business earns is taxed as personal income. If your practice earns $120,000 during the course of the year, you could take $60,000 of that as owner’s draws, or all $120,000—you’ll pay the same amount in income tax. The money is taxed as soon as you earn it.
Funds held in your business bank account should only be used for business expenses. Otherwise, you (or your bookkeeper) will be constantly sorting out personal expenses from business expenses. It makes day-to-day bookkeeping—not to mention taxes—a nightmare.
Once you transfer money from your business account to your personal account, and the transaction is labeled (in your bookkeeping general ledger) as an owner’s draw (an expense), you can spend it however you like.
You don’t pay any additional taxes on money you take as an owner’s draw, since it’s already taxed as personal income.
Taking an owner's draw may offer greater flexibility than paying yourself a salary. Even if you pay yourself with regular, recurring owner’s draws, you easily change their amounts or frequency in order to cover personal cash flow gaps.
How a salary works for therapists
Paying yourself a salary is very similar to being paid a salary by someone else. The only difference is that you’re the one in charge of entering it on the books, and processing it through payroll. (If you have a bookkeeper working for you, they’ll take care of this.)
On the personal side, when you receive a salary, your business automatically withholds income tax social security contributions. That money is remitted to the IRS.
On the business side, salaries are a tax deductible business expense, so long as they are:
- Ordinary and necessary
- An appropriate amount (more on how much to pay yourself below)
- Paid for services provided in the same tax year they’re deducted
If you’re unsure how payroll works, check out our guide to payroll for therapists.
One of the benefits of paying yourself a salary is that it may offer greater predictability and structure (ie. a paycheck every two weeks, versus an owner’s draw whenever you choose to take one).
How to pay yourself based on business structure
Different business structures have different requirements in terms of how you can pay yourself as a business owner.
How to pay yourself as a sole proprietor
If you’re a sole proprietor, you must pay yourself with an owner’s draw.
You must report your business’s income on Form 1040 (personal tax return), and pay taxes on it. Money you transfer as an owner’s draw will not be taxed a second time.
How to pay yourself in a partnership
If you are part of a partnership, a portion of revenue and expenses is passed on to your person according to your ownership share.
For instance, if you own 50% of the company, and your business partner owns the other 50%, half of your group practice’s revenue and expenses will appear on your personal tax return.
Partnerships report their income on Form 1065. Your personal share of the partnership’s income is reported on Schedule K-1. You pay taxes on the amount reported there.
You are not required to take all of that as an owner’s draw. For instance, if you owned 50% of the practice, and the practice earned $120,000 income, you’d report $60,000 income on your personal tax return. (The same amount would be reported on Schedule K-1.) But you could choose to take only $40,000 as an owner’s draw.
No matter how much you take as an owner’s draw, you must pay taxes on all income passed on from the partnership to your person.
How to pay yourself with an S corporation
If your private practice is an S corporation, you can pay yourself with a salary, with a distribution, or with both.
A distribution is a portion of profits passed on to shareholders in an S corporation. Typically, when someone owns part of an S corporation, but isn’t involved in day-to-day operations, they’ll take a distribution.
However, if you are involved in day-to-day operations—that is, you’re a practicing therapist working at a private practice you own or co-own—it makes sense to pay yourself a salary as an employee.
In that case, everything you earn is processed through your therapist practice’s payroll; income tax is withheld and remitted to the IRS.
You may also choose a third option: Receiving both distributions and a salary from your private practice. This lets you earn a regular paycheck, while earning extra when your practice is performing well. To set yourself up for both distributions and a salary, it’s best to get help from an accountant.
How S corp income is taxed
When your therapy practice is an S corporation, only the personal income you earn in the form of a salary is subject to self-employment tax. The remainder of your S corp’s income is not. Self-employment tax is equivalent to 15.3% of your earnings.
For example, if one year your S corp earned $120,000, and you received $80,000 as salary, only the $80,000 would be subject to a 15.3% tax (a total of $12,240). The remaining $40,000 would not.
Contrast this with a sole proprietorship: If your sole prop earned $120,000, and you took $80,000 as an owner’s draw, both the $80,000 and the remaining $40,000 would be subject to income tax. Your total self-employment tax would be 15.3% of $120,000, or $18,360.
Because S corp owners can significantly reduce their tax burden by cutting themselves small paychecks, the IRS pays special attention to S corp owner-employee salaries. If they determine that your salary is too low, they could reassess your tax return and charge you a higher self-employment tax bill.
To avoid this, you need to pay yourself a reasonable salary—compensation appropriate for your position, duties, and level of experience. Setting a reasonable salary can be tricky—it’s a good idea to consult with an accountant—but here are some resources to get yourself started:
- How to Calculate a Reasonable Salary as an S Corp Therapist
- S Corp Tax Savings Calculator for Therapists
- The Complete S Corp Guide for Private Practice Therapists
How to pay yourself with a limited liability company (LLC)
LLCs are administered on the state level. There’s no federal tax form to file taxes as an LLC. Rather, you can elect to file as a partnership, S corporation, or C corporation. The way you’re able to pay yourself varies accordingly.
How much should you pay yourself as a therapist?
If you’re paying yourself a salary from your therapy practice, it can be difficult to decide on an amount. For the sake of writing off your salary as a tax deductible expense, it can’t be too high or too low. Otherwise, you may increase your risk of being audited by the IRS. Even if you’re paying yourself owner’s draws from a sole proprietorship and you aren’t concerned with meeting IRS requirements for a reasonable wage, it can be difficult deciding how much to pay yourself.
Besides paying your salary and covering your practice’s other day-to-day expenses, your revenue can be used to:
- Save up to cover your living costs during a leave of absence
- Reinvest in the form of marketing for your business
- Eventually expand the services you offer by hiring employees
- Put aside money in case of a rainy day or unexpected shortfall
- Prepare for seasonal changes in revenue, like the summer slowdown
You can work out how much to pay yourself by planning out allocations with the help of an accountant or your accounting team at Heard.
Income Allocations (example)
According to Heard’s 2026 Financial State of Private Practice Report, therapists’ median revenue in 2025 was $80,412. Median revenue varied based on years of experience:
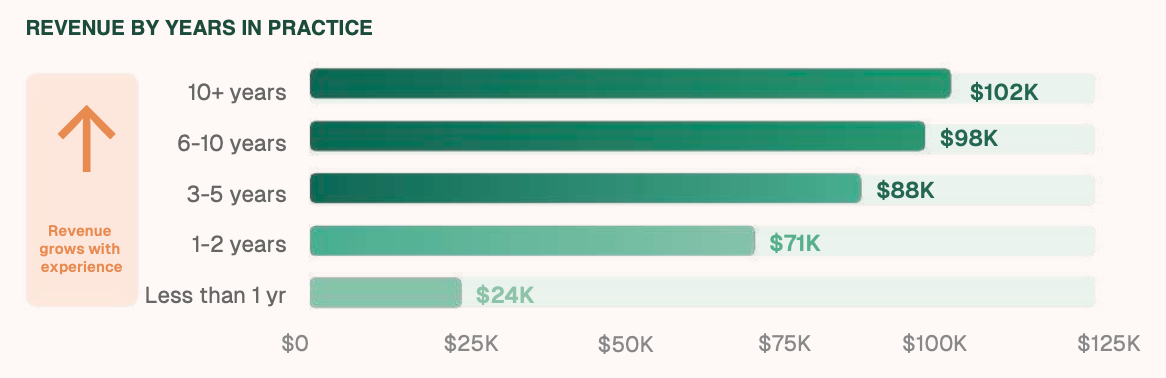
Those numbers are a helpful starting point, but there are other factors to take into account when setting your salary as a therapist:
Plans for expanding your therapy practice
Are you planning to hire staff, or move to a bigger or more permanent office space? If so, you should consider how much of your earnings you’ll need to reinvest in your practice to make it happen.
Emergency funds for your therapy practice
In the event of unforeseen circumstances—a recession, a COVID lockdown, or events in your personal life that prevent you from working—how much money would you need to keep your business running for six months? For a year? Cash you may be tempted to withdraw as a personal salary may be better diverted to a savings fund.
Therapist seasonal ups and downs
You may typically see an influx of new clients every January, as people fulfill their New Year’s resolutions to work on their mental health. Or perhaps during certain times of year there are more opportunities for supplemental income, such as conferences or retreats. Anticipating increases or decreases in income can help you set a sustainable personal salary.
How to determine a reasonable salary for therapists
There's no one-size-fits-all number, but your reasonable salary is generally based on:
- Your level of certification
- How much experience you have as a therapist
- How long you've been in business
- Your hourly rate
- Living expenses in your area
- Business operating expenses in your area
- The level of demand for therapy in your area
Look at what therapists with comparable skills and experience are earning where you practice. A Google search for "therapist salary in [your city]" can offer a rough estimate, and Heard's rate benchmarking calculator can help you see how your rates and income compare to other therapists with a similar profile.
You may also choose to consult with an accountant who works with other therapy practices.
It’s worth taking all of these into account, even if it’s only your first year in business as a solo practitioner. The work you do for your business, and the work you pay yourself for, is an investment in the future. Preparing now for professional ups and downs in the future may mean cutting yourself a smaller paycheck now, but it pays off in the long run.
—
When it comes to paying yourself, having separate bank accounts for personal and business income and expenses is essential. Heard Banking is built for exactly this—every transaction is automatically categorized and synced to your bookkeeping. Learn more about bank accounts for therapists, and make sure your owner's draw and salary are built into your therapy practice budget so your cash flow stays healthy.
Visit our Therapist Tax Center and Tax Deductions for Therapists Hub for everything you need to know about taxes as a practice owner. If you're just starting out, here's everything you need to know about How to Start a Private Practice as a Therapist.
This post is to be used for informational purposes only and does not constitute legal, business, or tax advice. Each person should consult their own attorney, business advisor, or tax advisor with respect to matters referenced in this post.
*Heard Banking is a financial technology company, not a bank. Banking services provided by i3 Bank, Member FDIC. Banking technology powered by Unit Finance, Inc. The Heard Visa Debit Card is issued by i3 Bank pursuant to a license from Visa U.S.A. Inc. and may be used everywhere Visa debit cards are accepted. Deposits may be eligible for up to $3 million of FDIC insurance through a network of participating banks. Each participating bank is FDIC insured up to $250,000 per depositor, per bank. Accounts are eligible for pass-through deposit insurance only to the extent pass-through insurance is permitted by the rules and regulations of the FDIC, and if the requirements for pass-through insurance are satisfied.
Bryce Warnes is a West Coast writer specializing in small business finances.
{{resource}}
Manage your bookkeeping, taxes, and payroll—all in one place.

Discover more. Get our newsletter.
Get free articles, guides, and tools developed by our experts to help you understand and manage your private practice finances.
We help you determine how much to pay yourself and set aside for taxes each month. Book a free consult to learn more.
Schedule a free consult